Why a tax time file system matters before the deadline
A tax time file system AU UK simple annual routine is less about perfect stationery and more about reducing decisions at the worst possible moment. When receipts, bank statements, adviser notes, rental property costs, work expenses and family documents sit in different inboxes, tax time becomes a memory test. The better aim is a calm system that tells you what to save, where it belongs, who can access it, and when the year is ready for review.
This matters in Australia and the United Kingdom because families often hold records across employers, pensions or superannuation, banks, investment platforms, property managers, charities, accountants and government portals. The rules differ between AU and UK tax systems, but the home routine can be similar: capture documents as they arrive, sort them into predictable folders, protect sensitive details, and leave a short note that another trusted person could understand. That note is especially useful when a partner, adult child, executor or adviser has to help during illness, travel, bereavement or a deadline.
Start by treating tax records as part of life admin, not a once-a-year panic. Evaheld's getting your affairs in order checklist shows how financial records, family instructions and important documents work together. The official UK self assessment filing service also makes clear that filing depends on having the right information ready, not simply opening a portal on the final day.
What should your annual tax folder include?
Your annual folder should answer four plain questions: what money came in, what costs may be relevant, what evidence supports those figures, and what has already been lodged or paid. For many households, that means salary or pension information, interest and dividend statements, rental income and expenses, work-related deductions, charitable giving, health or care costs where relevant, private health or insurance documents, business receipts, capital gains records, tax agent correspondence and final notices from the tax authority.
Create one top-level folder for the tax year, then use subfolders that match how you actually think. A family with employment income might use income, deductions, donations, health, investments, property, adviser, lodged return and carry-forward notes. A contractor or sole trader may need sales, expenses, invoices, vehicle, equipment, subscriptions, bank feeds, tax office letters and quarterly reviews. The point is not to copy someone else's filing cabinet. The point is to make every document easy to place in under thirty seconds.
For the AU side, keep labels that make sense around the Australian financial year. For the UK side, keep labels that make sense around the UK tax year. If your family has records in both countries, use country prefixes such as AU income and UK income so nobody mixes dates, currencies or obligations. Evaheld's life admin system is useful here because tax files often sit beside wills, insurance, care documents and account lists. The IRS filing information is not an AU or UK rule source, but it is a clear reminder that accurate filing starts with organised source documents.
How do you build the monthly routine?
The monthly routine should be short enough that you will actually do it. Set one recurring appointment for the same week each month. Open your tax folder, save bank statements, download invoices, photograph paper receipts, move email receipts out of your inbox, and add anything that may affect the year: job changes, property repairs, adviser fees, business purchases, charity receipts, education expenses, medical costs, insurance changes or investment documents.
Use a naming pattern that sorts automatically. A simple pattern is year-month-supplier-purpose, such as 2026-02-electrician-rental-repair or 2026-03-charity-donation. Avoid clever abbreviations that only make sense today. If you have mixed AU and UK records, add the country at the start. If a document may matter for estate, care or family administration later, add a one-line note explaining why it was kept. That turns a folder from a storage dump into a working record.
The monthly routine is also when you remove noise. Delete duplicate scans, rename vague downloads, move personal photos away from tax records, and mark anything you need to ask an accountant. If you are sharing a household with a partner, carer or adult child, agree on one place where everyone can drop relevant documents. Evaheld's Essentials vault area supports that kind of family document structure without turning private financial records into a shared inbox. For households worried about scams around tax season, the ACCC scam warning material is a practical reminder to treat unexpected tax messages carefully.
What should happen at the quarterly check-in?
A quarterly check-in is where the system becomes reliable. Spend thirty to forty-five minutes checking whether each folder has the expected documents. Compare bank records with saved receipts. Make sure investment, property and business items have enough context for an adviser to understand them. If something is missing, chase it while the transaction is still recent. This is much easier than trying to reconstruct twelve months of decisions in a weekend.
Quarterly checks also help families notice planning changes. A new rental property, side business, redundancy, inheritance, overseas move, parental leave period, illness, separation, marriage or caring responsibility can change what records matter. It may also change who needs to know where documents are kept. Evaheld's family document organisation approach is useful because it asks whether loved ones could find the right information if you were unavailable.
Keep a tax-year summary note in plain English. It should list major changes, unusual expenses, documents still missing, adviser questions and any records that belong outside the tax folder, such as legal documents or care instructions. This note should not replace professional advice. It simply helps you, your accountant and your family understand the year. The NIST small business cybersecurity material is a useful prompt to review access and device security whenever business or sensitive financial records are involved.
How should digital and paper tax records work together?
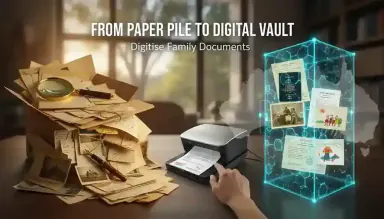
Digital records are easier to search, back up and share, while paper records are still useful for originals, handwritten notes and documents that arrive by post. A practical system uses both without duplicating everything. Keep a digital master file for the year, then keep a slim paper folder only for originals and items that need manual handling. Write the digital folder location on the front of the paper folder so the two systems stay connected.
When scanning, check that the full page is readable, the supplier and date are visible, and the file name makes sense. Do not rely on camera roll chronology. Photos disappear into thousands of unrelated images, and receipts fade. If you keep paper, separate documents by category with dividers or labelled envelopes. If you keep digital records, use folders rather than a single pile of PDFs. The test is simple: could someone else find the March charity receipt or the property repair invoice without asking you?
Security matters because tax records often include addresses, dates of birth, account numbers, income details and identity documents. Use strong passwords, multi-factor authentication where available, and a controlled sharing process. Evaheld's secure sensitive file sharing advice explains why family access needs boundaries as well as convenience. The UK cyber security basics offer a straightforward baseline for protecting accounts and devices.
How can AU and UK families handle cross-border records?
Cross-border households need extra clarity because tax years, terminology, currencies and filing triggers may differ. Keep separate AU and UK folders first, then add a shared folder for items that touch both countries, such as overseas bank interest, property costs, pension or superannuation material, employment moves, residency evidence, adviser letters and currency conversion notes. Do not assume a document belongs in only one country just because it was issued in one place.
Use plain country labels. AU bank interest, UK pension, AU rental repairs and UK self assessment letters are easier to scan than a single folder called finance. Keep copies of correspondence from advisers in the same country folder as the issue they discuss. If a professional gives advice, save the date, the adviser name and the scope of the advice. This is helpful later because family members can see whether a question was answered, deferred or still open.
Cross-border records also benefit from a family access map. A partner or executor should not have to know the tax law in two countries just to find the right adviser or folder. Evaheld's Australian data privacy and digital legacy planning can help families think about information sensitivity before they share documents. For a broad official view of tax administration tasks, the USA.gov tax overview is a useful reminder to keep filing evidence, payments and account access separate.
What is the year-end tax review checklist?
At year end, do a structured review rather than opening every file at random. First, confirm the tax year folder is complete. Second, check income records against bank deposits and employer, pension or platform statements. Third, review deductions and expenses category by category. Fourth, confirm documents are readable and correctly named. Fifth, move non-tax family records to the right place. Sixth, prepare a short adviser pack or self-lodgement checklist. Seventh, record what was lodged, when it was lodged, and where the final return or assessment is stored.
Use this checklist as a working routine:
- Confirm income records are complete for each country.
- Check receipts against bank and card statements.
- Separate personal spending from potentially deductible costs.
- Save annual statements from banks, platforms, employers and property managers.
- Label adviser questions before your appointment.
- Check whether any family member needs access to a copy.
- Store final lodged documents and payment confirmations.
- Write next year's improvements while the pain points are fresh.
This review is also a good time to connect tax records with broader family planning. If your executor or partner would need to understand your financial life, your tax folder may point to the accounts and assets they should know about. Evaheld's executor checklist planning helps turn that record trail into practical instructions. If you want one private place to organise the essentials, create a secure Evaheld tax records hub before the next tax year starts.
How do you protect family privacy while staying organised?
Good tax organisation should never mean careless sharing. Decide who needs access, what they need access to, and why. An accountant may need evidence for a deduction. A partner may need the annual folder and adviser details. An executor may need a map of accounts, tax identifiers and where final returns are stored. An adult child may need only emergency instructions. Sharing everything with everyone creates risk and confusion.
Use role-based folders where possible. Keep identity documents, tax identifiers and passwords separate from routine receipts. Do not put passwords in a tax folder. Do not leave scans of passports, tax file numbers, National Insurance details or bank accounts in email threads. If you must share by email, remove access afterwards and avoid forwarding chains that include old attachments. Evaheld's digital legacy vault is designed for controlled family access, not public storage.
Privacy also includes emotional privacy. Tax records can reveal donations, medical costs, family support, debt, separation expenses, business stress or income changes. Add context where it helps, but avoid turning a tax file into a diary. Keep the tone factual and kind. The FCA scam protection guidance is a useful UK reminder that financial information should be handled with caution, especially when messages create urgency around tax or refunds.
How can this routine support loved ones later?
A clear tax file system is a gift to future helpers. If you become unwell, travel unexpectedly, lose capacity for a period, or die, your family may need to work with advisers, locate account information, answer estate questions, deal with income records or close financial loops. They do not need every private detail on day one. They do need a map that shows what exists and who can help.
That map can be short. Include the folder location, accountant or tax agent details, tax authority account information, recent lodged return locations, property and business record locations, investment platform names, and any cross-border notes. Include what not to do as well: do not delete emails from this adviser, do not close this account before speaking to the executor, do not assume this folder contains legal advice. Those plain warnings prevent expensive mistakes.
For many families, the tax folder becomes a doorway into better life admin. Once financial records are organised, it is easier to organise insurance, estate planning, health wishes, care instructions, passwords and family stories. A calm system keeps practical tasks from crowding out relationships. It gives loved ones enough structure to help without making them decode years of private decisions under pressure.
For a practical next step, explore getting your affairs in order checklist.
For a practical next step, explore getting your affairs in order checklist.
For a practical next step, explore Evaheld planning resources.
For a practical next step, explore legacy planning resources.
For a practical next step, explore executor checklist.
For a practical next step, explore executor checklist.
For a practical next step, explore digital legacy.
For a practical next step, explore legacy.